Before choosing renovation financing, establish the work scope and the information needed to compare offers. A low advertised payment can conceal a different term, fee structure, or repayment risk.
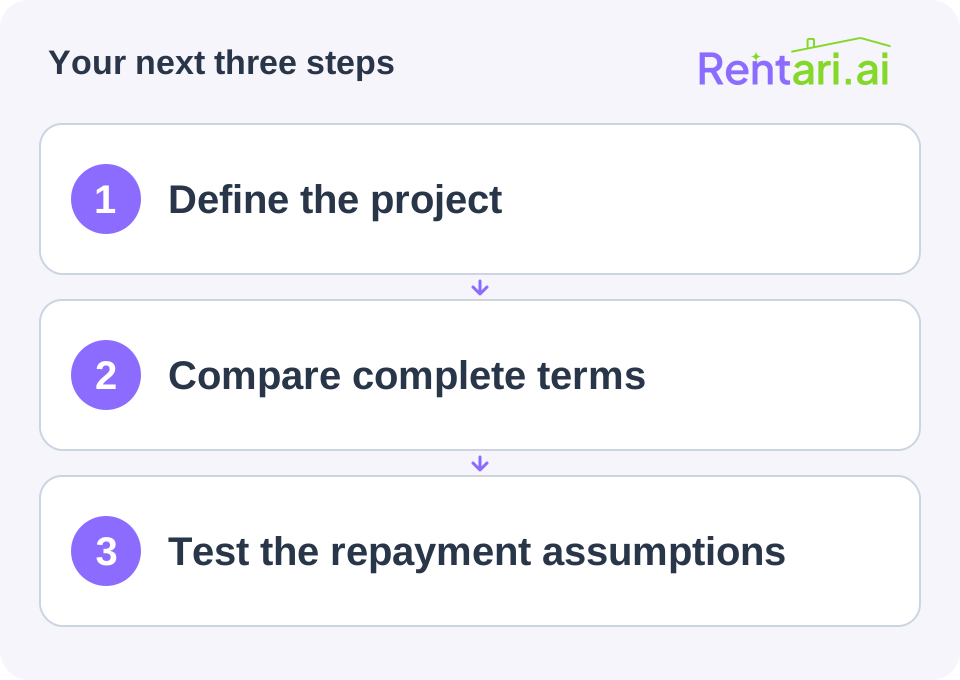
Define the project
Obtain realistic scope, quotes, permits where applicable, timing, contingency assumptions, and operational impact. Separate necessary work from optional improvements. Do not assume an unverified rent increase will fund the project.
Identify available cash and obligations with appropriate financial advice for your circumstances.
Request comparable terms
Record amount financed, rate, fixed or variable structure, fees, term, payment schedule, collateral, guarantees, prepayment conditions, and total repayment information. Ask how delayed draws or project changes affect cost.
The CFPB's mortgage comparison guidance illustrates why complete terms matter. Not every business-purpose or renovation product uses the same disclosures, so ask the lender what applies to the actual offer.
Review the downside
Consider what happens if work costs more, occupancy is delayed, or expected income does not materialize. Use realistic scenarios and qualified advice rather than a promised return.
Keep each offer and its assumptions dated. Before signing, resolve unclear terms with the lender and relevant professionals.
This is a preparation workflow, not a recommendation to borrow. The useful outcome is a comparison you can explain without relying solely on the monthly payment.
Sources and further reading
Source review: September 24, 2026. Check current requirements before acting.