A hypothetical owner receives a lower annual premium and considers switching immediately. The second quote has a higher deductible and different water-related terms.
Put the differences side by side
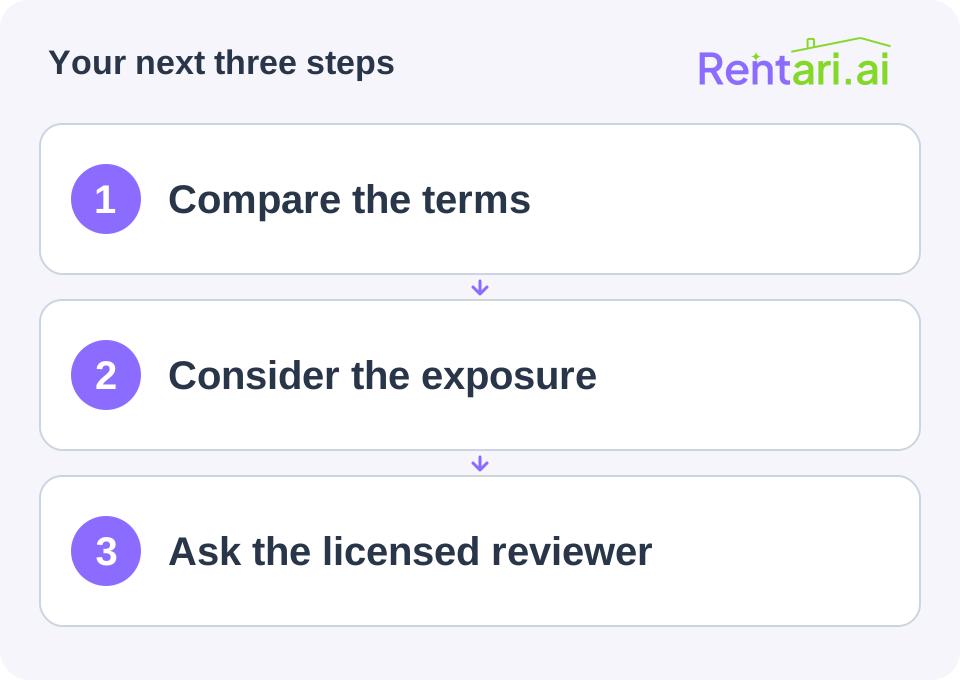
The owner records the premium, deductible, relevant exclusions, valuation, and endorsements. They check whether both quotes describe the same rental use and property details.
The price comparison remains incomplete until those differences are understood.
Ask a concrete question
The owner asks the licensed agent to explain how the differing provisions would apply to the property's relevant risks, using the actual policy wording. They do not rely on a general statement that the policies are basically the same.
Available cash for an out-of-pocket loss is considered with appropriate professional advice. No hypothetical claim outcome is treated as guaranteed.
Confirm the final arrangement
If a replacement is selected, the owner confirms its effective coverage and required conditions before canceling the old policy. The written comparison is retained for renewal.
The lesson is not that the cheaper policy is wrong. It is that premium alone does not describe the purchase.
For your next renewal, identify the three largest wording differences and resolve them with a qualified insurance professional before making the decision.
Sources and further reading
Source review: September 24, 2026. Check current requirements before acting.